
Last updated September 23, 2026
Free visual inspection and a written scope of work before any mitigation begins - photos, moisture readings, and drying logs go in your claim file
The scope we write is the scope we bill. Anything new gets shown to you, in writing, before we touch it.
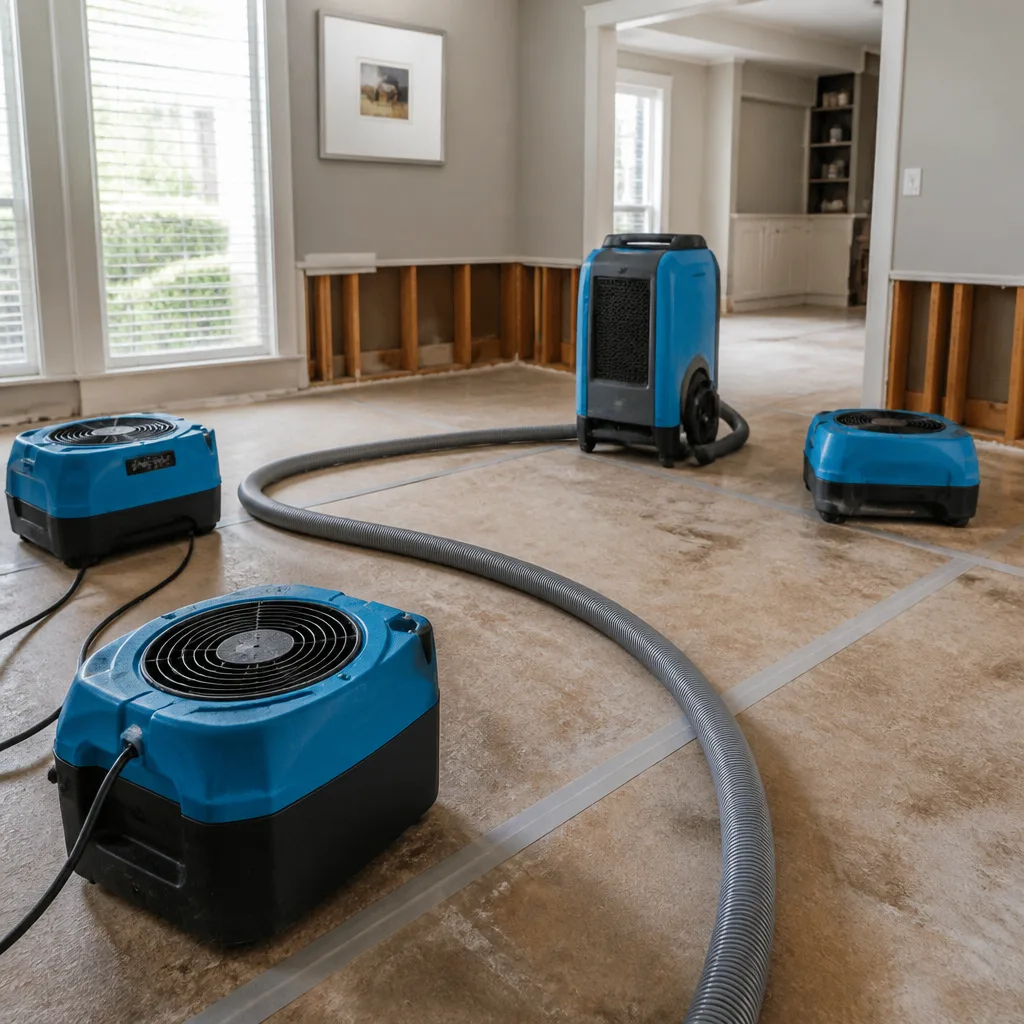
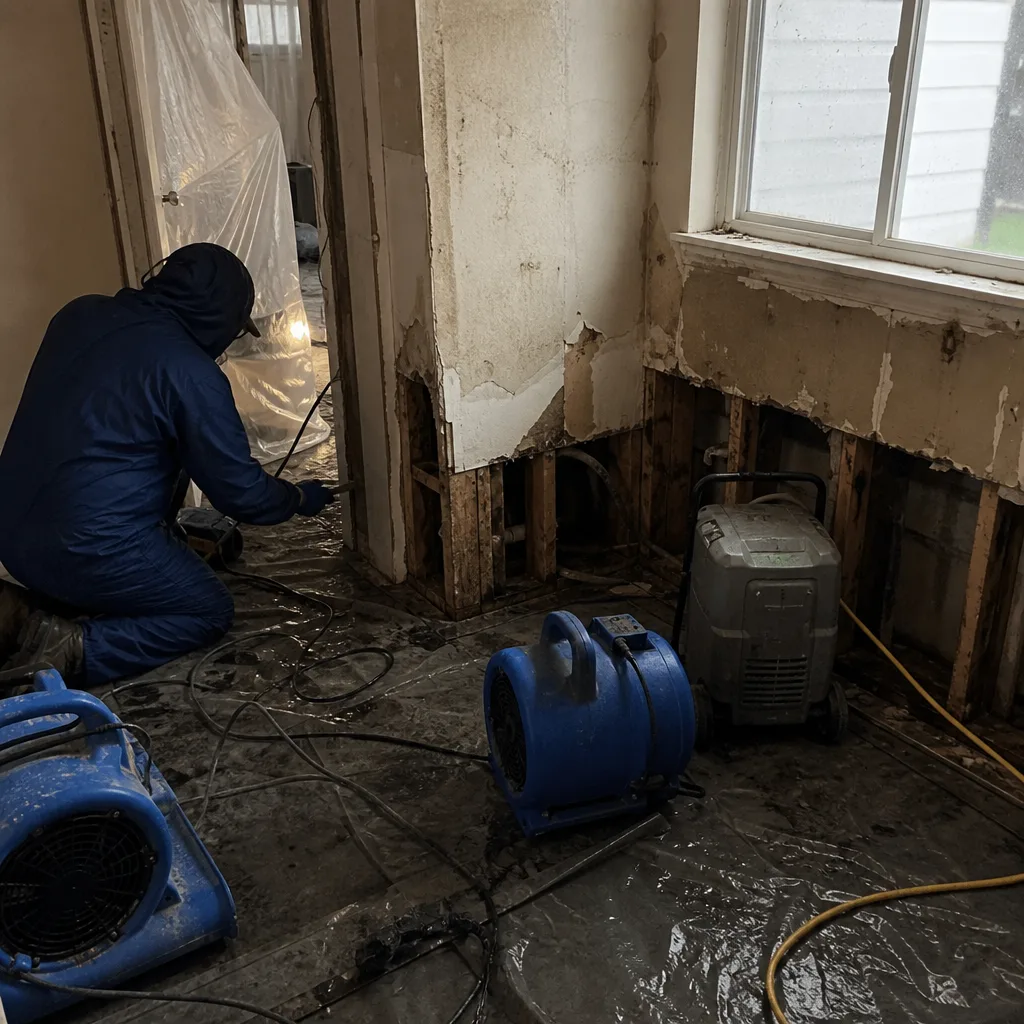 Before
 After
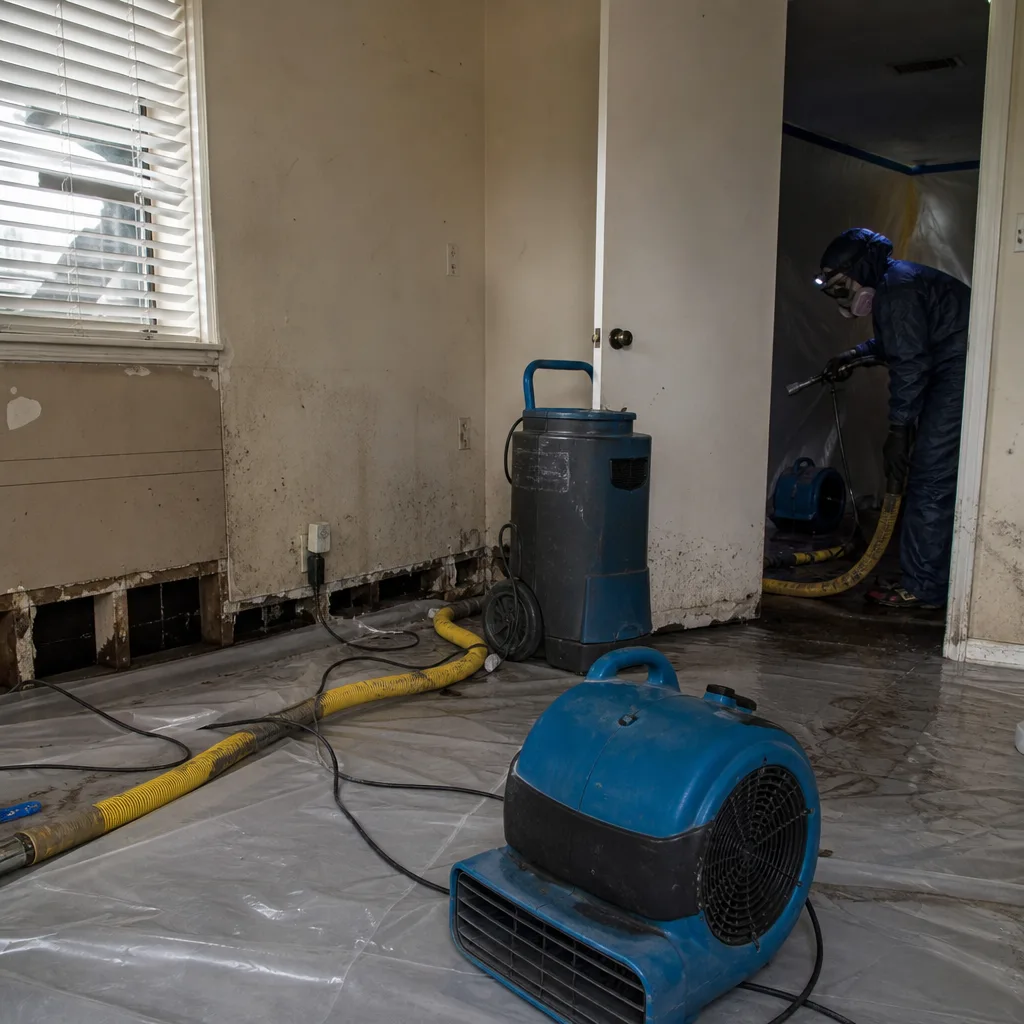 Before
 After
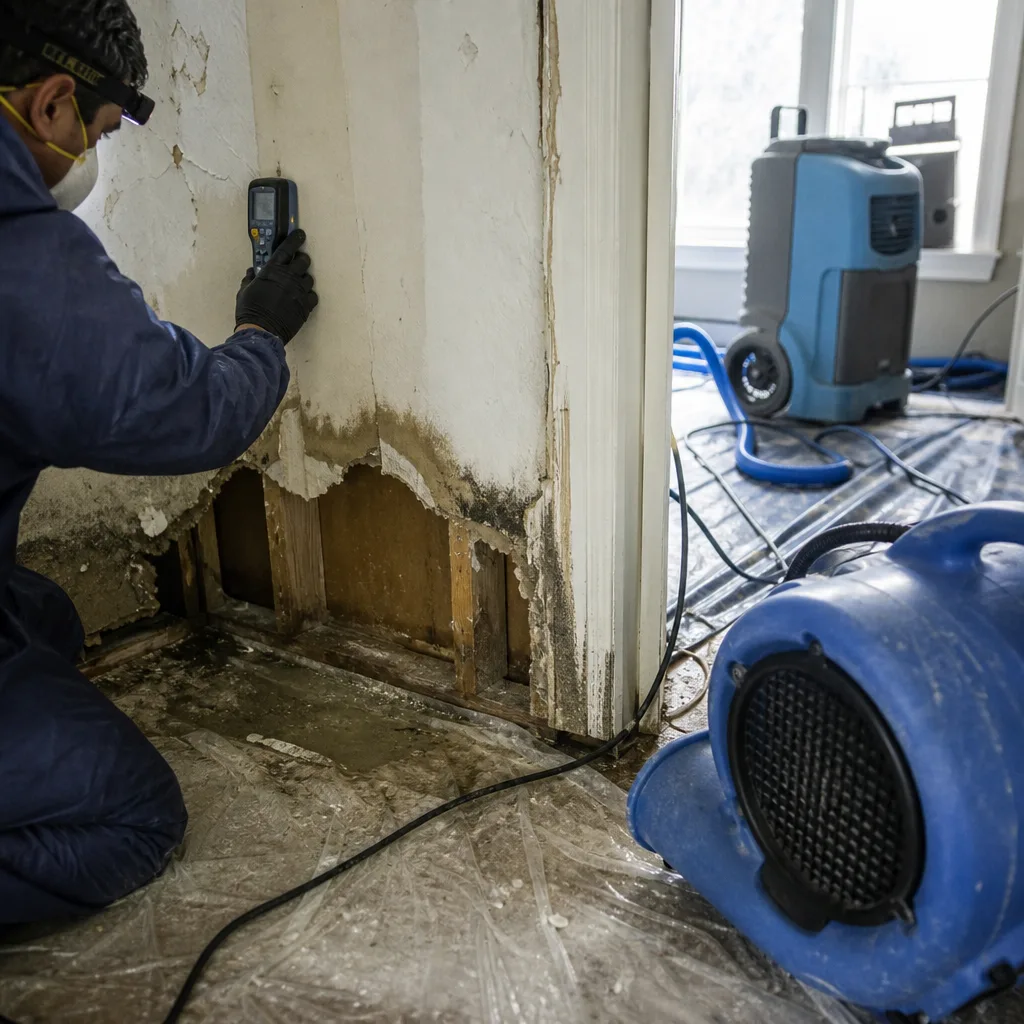 Before
 After
How to Hire a Damage Restoration Contractor in Los Angeles: A Step-by-Step Guide
Signing an Assignment of Benefits with a restoration contractor in California legally transfers your right to negotiate your own insurance claim - a fact that is rarely explained at the door at 11 p.m. when a pipe has just burst. In Los Angeles, where water damage claims from aging copper plumbing in Mid-Century homes and wildfire smoke intrusion events have both risen sharply since 2020, this single document can cost homeowners tens of thousands in uncovered repairs. This guide - alongside our Complete Guide to Damage Restoration in Los Angeles - walks you through verifying credentials, comparing bids by documentation quality rather than price, and keeping control of your claim from first call to final invoice.
Quick Answer
To hire a damage restoration contractor in Los Angeles, verify their CSLB license and workers’ comp certificate online, demand a written scope with itemized Xactimate pricing before any work begins, refuse any Assignment of Benefits or direction-to-pay requirement, and confirm they document every visit with dated photos and daily moisture logs. The lowest bid is rarely the cheapest outcome - incomplete scopes generate supplements that insurers dispute and homeowners pay out of pocket.
Table of Contents
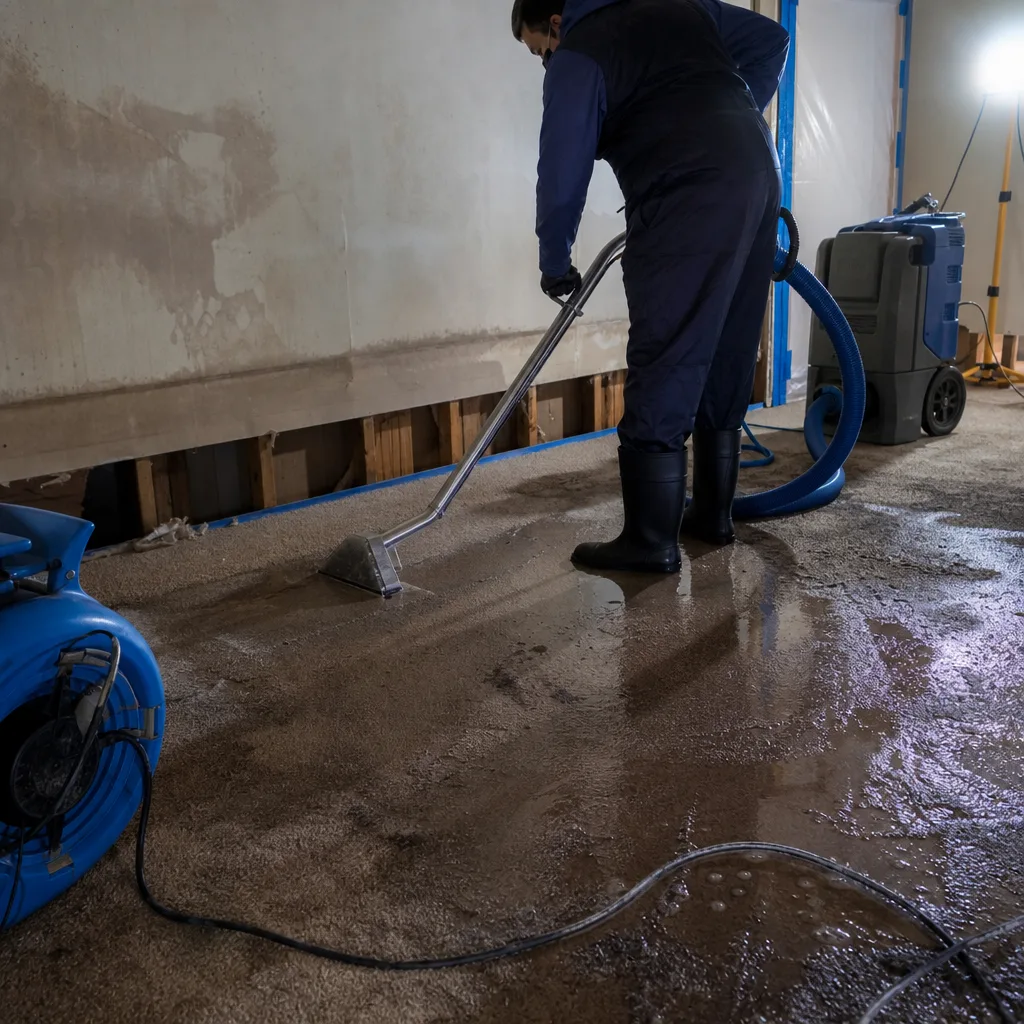
- How to Verify a Contractor’s License and Insurance in Under 10 Minutes
- The Four Contract Clauses That Protect Homeowners
- How to Judge Documentation Quality Before You Hire
- Why the Lowest Estimate Is Often the Most Expensive Outcome
- Los Angeles Red Flags: Storm Chasers, Unlicensed Crews, and Verbal Warranties
- Keeping Control of Your Insurance Claim
- Common Mistakes to Avoid
- When to Call a Professional
- Frequently Asked Questions
 Before
 After
How to Verify a Contractor’s License and Insurance in Under 10 Minutes
Every restoration contractor working in Los Angeles must carry a valid California State License Board (CSLB) license. For water damage and reconstruction work, look for a C-61/D-49 (Sewer, Septic, and Storm Drain) or C-36 (Plumbing) for mitigation; for structural rebuilds, a B-General Building or C-33 (Painting and Decorating) license. The license number should appear on every proposal, business card, and vehicle. If a crew arrives without it visible, that’s your first signal to stop the conversation.
Here’s the exact verification process we recommend to every homeowner who calls DryMark Restoration Los Angeles home:
- Check CSLB status: Go to cslb.ca.gov, enter the license number, and confirm “Active” status. Note the license expiration date and any pending disciplinary actions. A suspended license is common after complaints - don’t accept “it’s being renewed” as an answer.
- Verify workers’ compensation: On the same CSLB page, click “Workers’ Compensation” and confirm coverage is active. In California, an exempt status means the contractor has no employees, which is unlikely for a crew handling water extraction and demolition. If workers are injured on your property and coverage lapses, your homeowner’s policy becomes the target.
- Review complaint history: Scroll to “Complaint Disclosure” and read the nature of any filed complaints. Pattern complaints about incomplete work, unreturned deposits, or insurance billing disputes are predictive of your experience.
- Confirm bond status: The CSLB page lists the contractor’s bond company and amount. A $25,000 bond is standard; if it’s listed as “cancelled,” the contractor cannot legally perform work.
This entire check takes seven to ten minutes. Do it before anyone enters your home. In Los Angeles, unlicensed operators frequently advertise as “mitigation specialists” or “emergency response teams” to avoid CSLB scrutiny - they are not exempt from licensing requirements if they perform structural drying, demolition, or rebuild work.
At Back to Dry, our license number appears on every written scope, every vehicle, and every technician’s uniform. We background-check and name-verify every employee before they arrive. The license is not marketing - it’s the minimum legal threshold for entering your property with power tools and insurance liability.
The Four Contract Clauses That Protect Homeowners
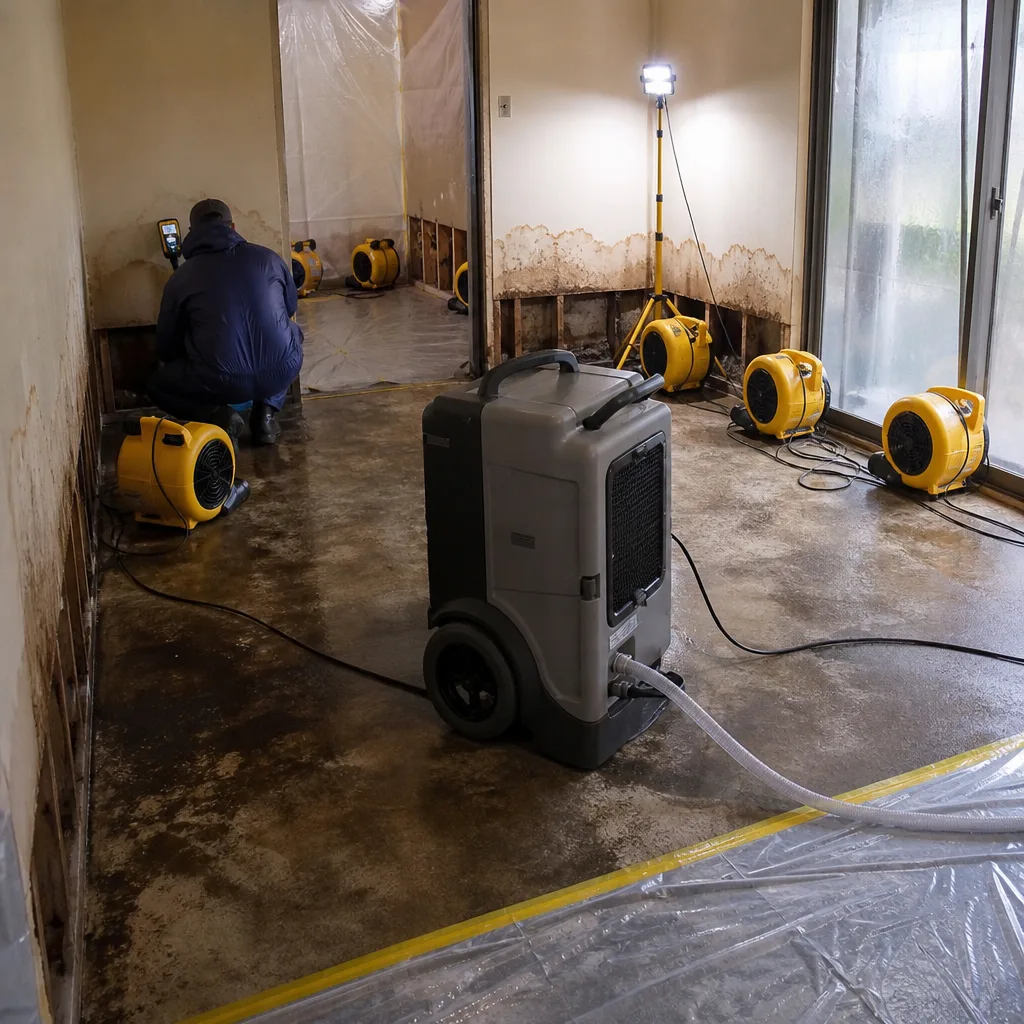
The written scope is where most homeowners lose control of their project. A generic one-page estimate with a single total and a signature line is not a scope - it’s a blank check. These four clauses, insisted upon before work begins, separate documented professionals from operators who profit from ambiguity.
Clause 1: Written Price Before Work Begins
Haven Standard, Clause 1: a written price is delivered before anyone starts work, every time, with no exceptions. This means line-item pricing for each phase - extraction, demolition, drying equipment, monitoring visits, and reconstruction - in a format your adjuster can read without interpretation. At Back to Dry, we use Xactimate, the same pricing database most insurers use, so the numbers on our scope match the numbers on their screens. No scope-creep additions once the crew is inside. If conditions change, we write a supplement with photos and get your signature before continuing.
Clause 2: Daily Moisture Log Delivery
Psychrometric data - temperature, relative humidity, and specific humidity readings - tells the story of whether your structure is actually drying or just circulating damp air. A daily moisture log records these readings room by room, along with moisture content percentages in wood framing, drywall, and concrete subfloors. Without this log, an insurer can claim drying was incomplete or excessive, denying portions of your claim. We deliver these logs as standard, not as an upsell. Ask any contractor to show you a sample log from a recent job. If they cannot produce one, they are not documenting to insurer standards.
Clause 3: No Assignment of Benefits or Direction-to-Pay Requirement
An Assignment of Benefits (AOB) transfers your right to receive insurance payments directly to the contractor. A direction-to-pay instructs your insurer to send checks to the contractor’s address. Both documents seem convenient - until the contractor submits a supplement you dispute, or performs work you didn’t authorize, and you have no standing to negotiate with your own insurer. In California, AOBs are legal but heavily restricted after 2019 reforms. Some contractors still use them for “emergency” work, knowing homeowners sign under stress. We have never required an AOB or direction-to-pay in 12,000 jobs. Your claim is your property.
Clause 4: Itemized Final Invoice in Xactimate or Equivalent Format
The final invoice must match the written scope line for line, with additions documented by change order and photo evidence. Xactimate format matters because it eliminates translation disputes - your adjuster sees the same unit prices, the same material codes, the same labor rates that we do. An invoice in a proprietary spreadsheet or handwritten format invites scrutiny and delay. Our final invoices include the photo record from every visit, cross-referenced to drying log dates, so the documentation chain is unbroken from first moisture reading to last payment.
How to Judge Documentation Quality Before You Hire
Documentation is the product. The drying equipment, the demolition, the rebuild - these are visible outcomes. But the documentation determines whether your insurer pays for them. In Los Angeles, where median home values in neighborhoods like Silver Lake, Los Feliz, and Venice Beach exceed $1.5 million, an underpaid claim can leave a homeowner with a $40,000 gap between damage and coverage.
Ask these three questions before signing any agreement:
- “Can I see a sample drying log from a recent job?” A legitimate contractor produces this immediately. The log should show daily readings with equipment serial numbers, psychrometric calculations, and a clear drying goal (typically 12-16% moisture content for wood framing). If the sample is vague or missing dates, expect the same on your job.
- “What psychrometric data do you record, and how do you use it?” The answer should include specific humidity grains per pound, vapor pressure differential between affected and unaffected areas, and dew point calculations. These measurements determine equipment placement and duration. A contractor who says “we just run the fans until it feels dry” is guessing with your structure.
- “How do you handle a scope supplement?” Supplements are routine in restoration - hidden damage reveals itself during demolition. The proper process is: photo documentation, written explanation, revised Xactimate line items, homeowner signature, then submission to insurer. A contractor who says “we just bill for whatever we find” is inviting claim denial and balance billing to you.
At Back to Dry, our documentation package on every job includes: the written scope with Haven Standard Clause 1 pricing, the daily moisture log with psychrometric data, dated photo records from every visit, and the final invoice with cross-referenced documentation. This package is not an upsell. It is the reason 12,000 claims have been paid without the fights that consume homeowners who hired cheaper, undocumented bids.
Our equipment - Dri-Eaz dehumidifiers, Phoenix air movers, and Injectidry cavity drying systems - produces the raw data. The documentation turns that data into a payable claim. Water Damage Restoration in Los Angeles requires both; neither alone is sufficient.
Why the Lowest Estimate Is Often the Most Expensive Outcome
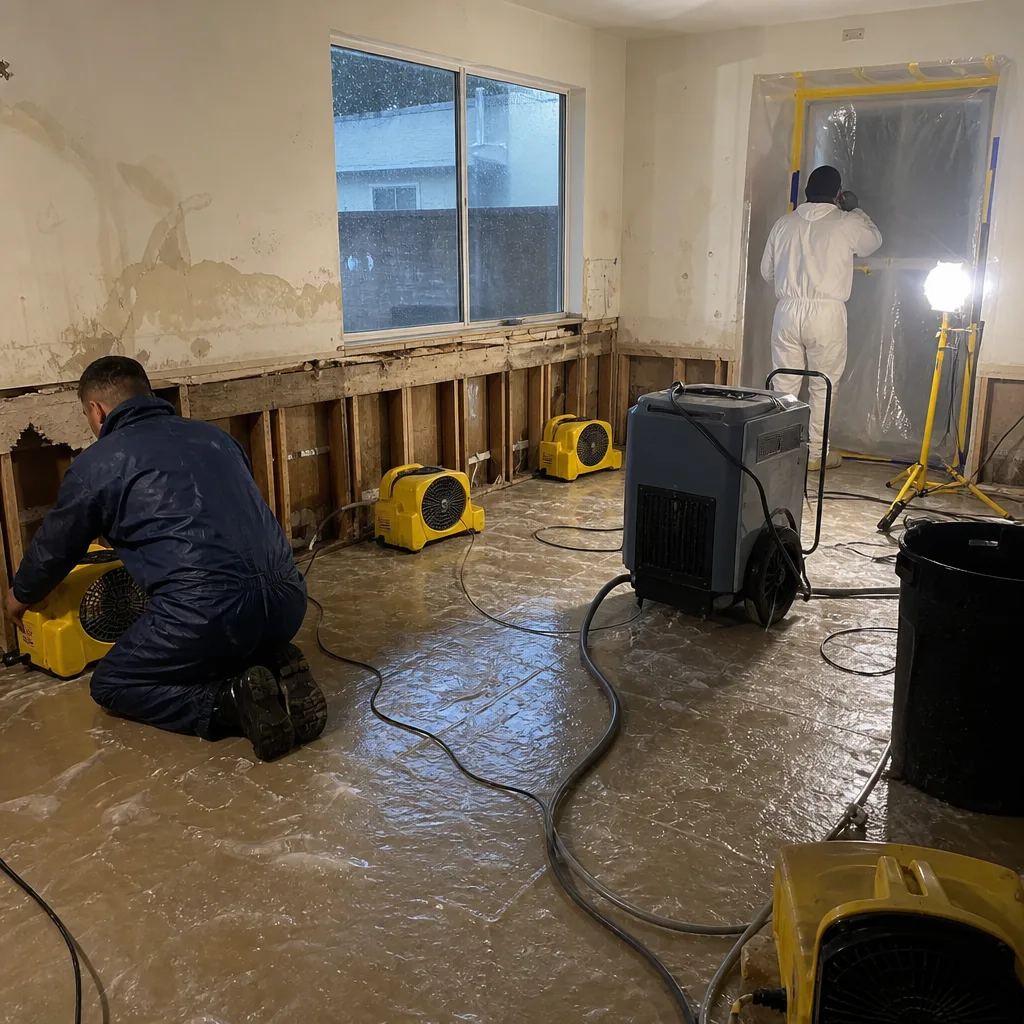
Restoration bids in Los Angeles vary widely - from $2,800 for a contained water loss to $45,000+ for a multi-room flood with category 3 contamination. The temptation is to select the lowest initial estimate and hope for the best. This is where most homeowners incur out-of-pocket costs that exceed any premium they saved.
Here’s why: an incomplete initial scope misses affected areas that become visible only after demolition. A contractor who bid low to win the job then submits supplements without proper documentation. The insurer denies the supplement for lack of evidence. The contractor, now underwater on the job, either abandons the work or bills the homeowner directly. The homeowner pays twice: once for the incomplete work, again for the contractor who finishes it properly.
Compare bids by these line items, not by total price:
| Line Item | What to Look For | Red Flag |
|---|---|---|
| Moisture mapping | Room-by-room readings with meter type specified | “Visual inspection only” or no mention |
| Equipment count | Specific dehumidifier and air mover quantities by brand | Generic “drying equipment” with no count |
| Monitoring visits | Daily or every-other-day visits with documented readings | “As needed” or no visit count |
| Demolition scope | Specific materials, square footage, and disposal method | “Demo as required” open-ended language |
| Reconstruction | Line-item materials and labor by trade | Single lump sum with no breakdown |
| Documentation | Daily logs, photo record, final report specified | No mention or “available upon request” |
A bid with complete line-item documentation will almost always total higher than a vague lump-sum estimate. It will also almost always result in lower out-of-pocket costs, because the insurer can process it without dispute and the homeowner can verify completion against the written scope.
Back to Dry offers a Free Second Opinion on any competitor’s written estimate. Bring us a scope from another contractor and we will review it for completeness, documentation standards, and pricing accuracy - at no charge. In our experience, roughly 40% of competitor estimates we review omit necessary monitoring visits or understate equipment counts, both of which generate supplements later.
Los Angeles Red Flags: Storm Chasers, Unlicensed Crews, and Verbal Warranties
Los Angeles presents specific contractor risks that hiring guides for other markets miss. Understanding these local patterns - detailed in our Seasonal Damage Restoration Care for Los Angeles: Year-Round Homeowner’s Guide - protects homeowners from the surge operators who follow disaster headlines.
Post-Disaster Contractor Surge
After major wildfires, Santa Ana wind events, or significant rainstorms, out-of-state restoration companies descend on Los Angeles with temporary CSLB registrations and local subcontractor arrangements. These operators typically:
- Use license numbers from other states or counties, valid for emergency work but with no local accountability
- Rent equipment locally rather than owning maintained systems, leading to inconsistent drying performance
- Disappear before final invoice resolution, leaving homeowners to manage insurer disputes alone
- Pressure-sign AOBs at the door, knowing stressed homeowners won’t verify credentials
Verify any post-disaster contractor’s physical Los Angeles address, not just a P.O. box or shared office. Ask how long they’ve maintained local equipment inventory. Back to Dry has operated from the same Los Angeles base since 2011, with owned equipment from Dri-Eaz, Phoenix, XPOWER, and B-Air maintained on-site.
Unlicensed “Mitigation Only” Crews
A common evasion in Los Angeles is the unlicensed operator who performs “mitigation only” - extraction and equipment placement - then refers reconstruction to a licensed contractor. This splits liability and documentation: the unlicensed crew produces no drying logs, the licensed contractor has no visibility into initial conditions, and the homeowner holds two incomplete records. California requires licensing for any structural drying that includes demolition or material removal. “Mitigation only” is not a legal exemption.
Verbal-Only Mold Warranties
Los Angeles’s combination of ocean humidity, Santa Ana heat cycles, and aging construction creates persistent mold risk in previously water-damaged properties. Contractors who offer verbal assurances - “we guarantee no mold” - without written post-remediation verification are selling fiction. A valid mold warranty requires: third-party post-remediation air sampling, written clearance documentation, and a specified re-inspection period. At Back to Dry, Mold Remediation in Los Angeles includes written clearance as standard under The Haven Standard, not as an optional add-on.
Keeping Control of Your Insurance Claim
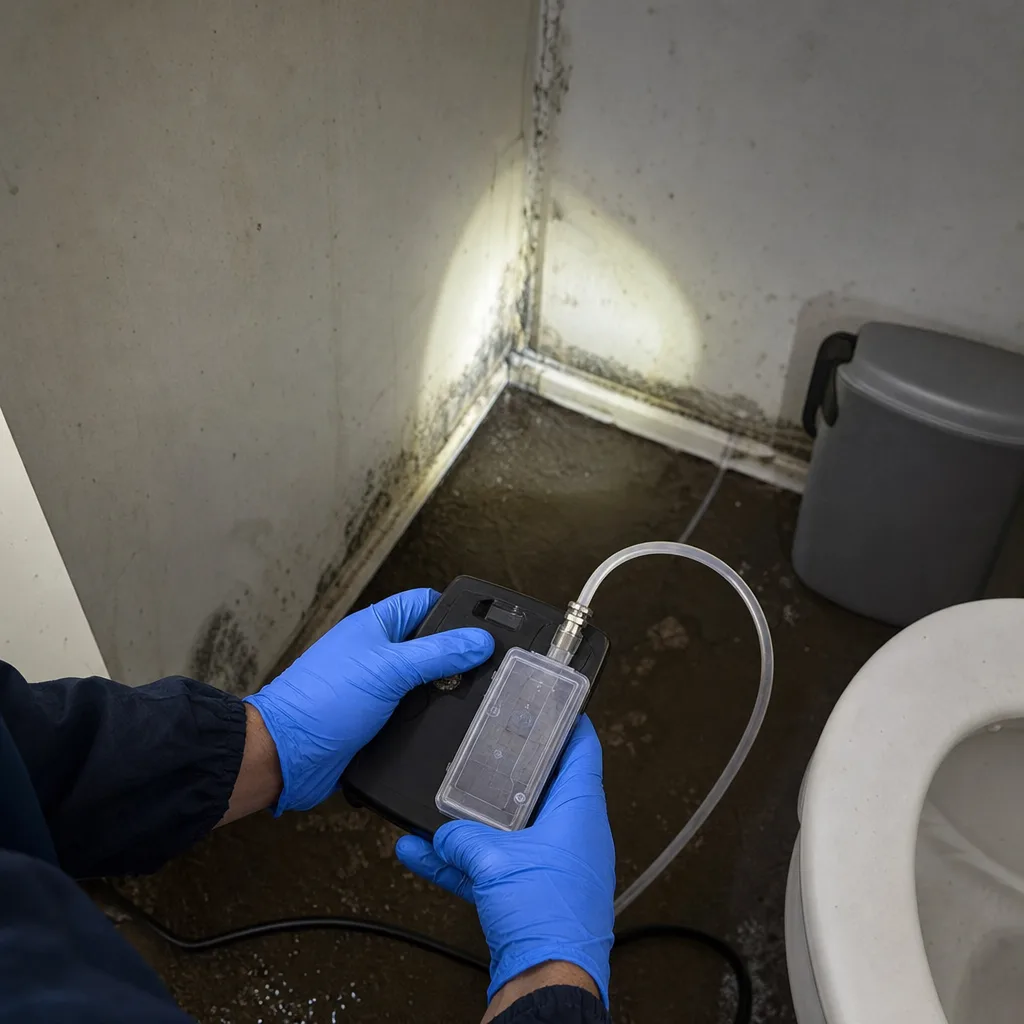
The restoration contractor and the insurance adjuster are not adversaries, but they are not aligned either. The contractor wants to perform and bill for complete work. The adjuster wants to pay the minimum justified by documentation. The homeowner sits between them, and whoever controls the documentation controls the outcome.
Here’s how to maintain that control:
- Photograph everything before the contractor arrives. Your own photo record of the loss, timestamped and geotagged, establishes the baseline that contractor documentation must match. If walls are opened and the contractor’s photos begin mid-demolition, you have no independent verification of original conditions.
- Request direct insurer communication. Your policy requires you to cooperate with your insurer’s investigation. It does not require you to route all communication through your contractor. Maintain your own claim file with adjuster contact information, claim number, and correspondence copies.
- Review every supplement before signature. A supplement is a change to the written scope. It should include photos of the newly discovered damage, written explanation of why it was not visible initially, and revised line-item pricing. Do not authorize work beyond the original scope without this documentation.
- Receive payments directly. Your insurer will issue payments to you as policyholder. You then pay the contractor per the written scope. This preserves your leverage to ensure completion and your right to dispute charges. Any contractor who insists on direct payment from your insurer is asking you to surrender this leverage.
At Back to Dry, we coordinate directly with adjusters - sharing our documentation, answering their questions, attending site visits when requested - but we do not accept payment assignment. Haven Standard, Clause 1 requires your signature on every scope and supplement. Your claim remains your property throughout.
For Fire & Smoke Damage Restoration in Los Angeles, this documentation control is especially critical. Smoke damage claims involve complex scope disputes - thermal fogging versus ozone treatment, structural versus contents cleaning, temporary relocation costs - that generate more supplements than water losses. A contractor who handles adjuster communication transparently, with full documentation shared to the homeowner, prevents the claim drift that leaves families in extended hotel stays.
Common Mistakes to Avoid
- Signing an AOB under time pressure. In Los Angeles, burst pipes and wildfire evacuations create genuine urgency. But a signature at 11 p.m. can surrender claim rights that take months to recover. Pause, verify the license, and read every document. A legitimate contractor will wait ten minutes.
- Accepting a verbal estimate. California law requires a written contract for home improvement work over $500. A verbal “we’ll figure it out” estimate is unenforceable and almost always exceeds the initial number. Haven Standard, Clause 1 exists to prevent this.
- Hiring based on response speed alone. Fast arrival matters for water mitigation - every hour of standing water increases damage. But speed without documentation produces fast, incomplete work. Ask about documentation process before asking about arrival time.
- Ignoring the drying log. Homeowners often focus on visible demolition and reconstruction while neglecting the invisible drying phase. An incomplete dryout causes mold, structural decay, and claim disputes years later. Request and review the daily moisture log as actively as you review paint colors.
- Comparing total prices without comparing scopes. A $8,500 bid and a $12,000 bid are not comparable without line-item review. The lower bid may omit necessary monitoring, understate equipment, or exclude reconstruction. The higher bid may include documentation standards that prevent later supplements.
- Failing to verify workers’ comp for subcontractors. Many restoration contractors use subcontracted labor for demolition or reconstruction. Verify workers’ comp for the primary contractor and ask for certificates for any subcontractor who will enter your home.
- Neglecting post-completion verification. For mold remediation, demand third-party clearance testing. For water damage, request a final moisture reading report showing all materials within specification. A contractor who resists this verification has something to hide.
When to Call a Professional
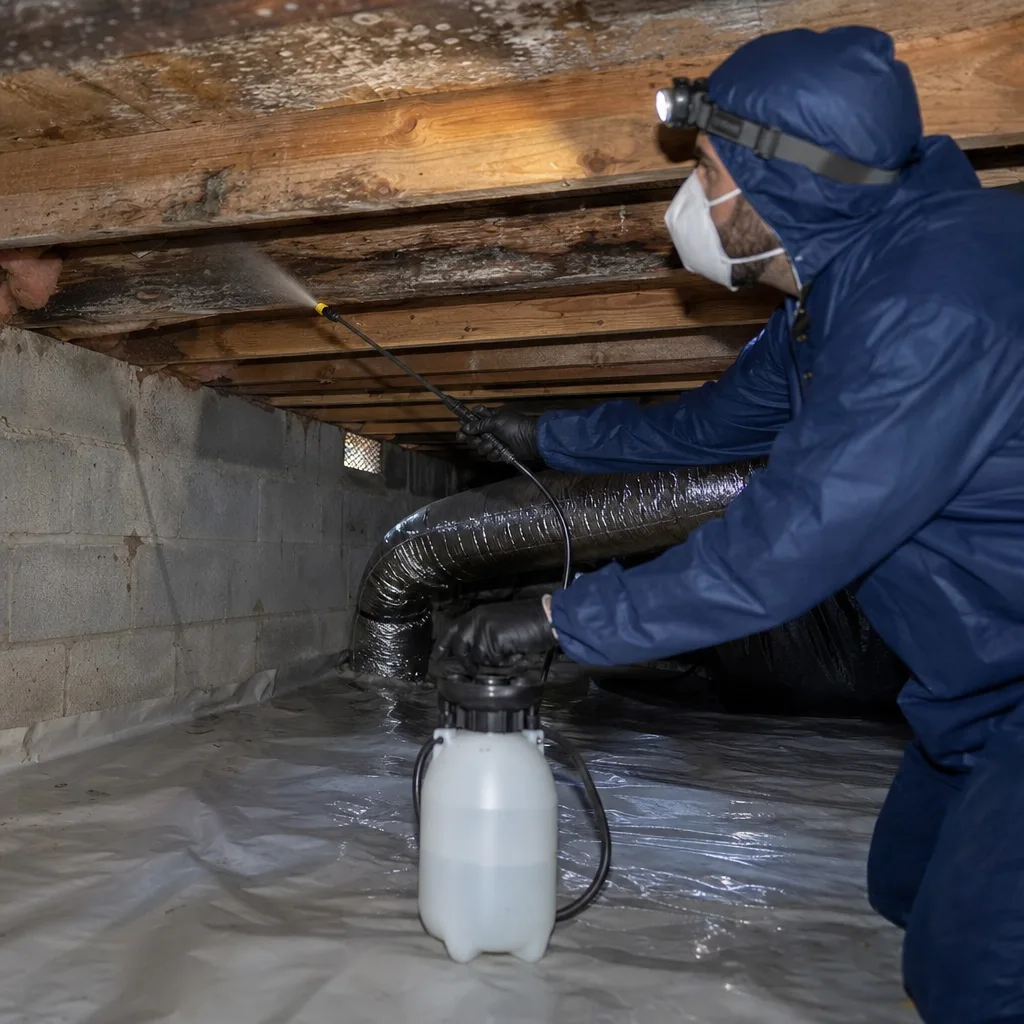
Some damage scenarios in Los Angeles require immediate professional response regardless of your DIY capability. Category 3 water damage - sewage backup, seawater intrusion, or standing water exceeding 48 hours - carries bacterial and chemical contamination that standard household cleaning cannot address. DryMark Restoration Los Angeles offers free estimates in Los Angeles - call (424) 351-3396. Fire damage with structural compromise, smoke damage affecting HVAC systems, and mold growth exceeding ten square feet all require containment protocols and documented remediation that homeowners cannot safely perform.
In our experience, the homeowners who fare best are those who call early, document thoroughly, and maintain control of their claim documentation. The ones who struggle delay the call, accept the first contractor at the door, and discover problems when the insurer denies a supplement they never reviewed.
Frequently Asked Questions
Water damage restoration in Los Angeles typically ranges from $3,200 for a contained single-room loss to $38,000 for a whole-house category 3 flood with reconstruction, based on 2024-2025 market rates for labor and materials. See our Water Damage Restoration Maintenance Checklist for Los Angeles Homeowners for prevention steps. Category 1 clean water losses with prompt response fall at the lower end; category 3 sewage losses with delayed discovery and mold secondary damage fall at the upper end. Every job at Back to Dry receives a written Xactimate scope before work begins - call (424) 351-3396 for an exact quote; estimates are free.
Insurance coverage depends on your policy’s per-incident limit, your deductible, and whether the damage resulted from a covered peril. In Los Angeles, burst pipes and accidental discharge are typically covered; gradual leaks and flood damage from external sources often are not. The key factor in full coverage is documentation quality - complete drying logs, photo records, and itemized Xactimate invoices that match insurer pricing databases. Back to Dry documents to IICRC, RIA, and IFA standards specifically to produce payable claims.
For water damage mitigation, Back to Dry maintains live phone coverage 24 hours a day, 7 days a week with no voicemail on emergency lines, and dispatches crews for active water losses within the hour in most Los Angeles neighborhoods. Reconstruction and non-emergency work is scheduled, not dispatched - scoped, priced in writing, and placed on the calendar like any professional construction project. Call (424) 351-3396 to confirm current availability for your situation.
For water damage, DIY extraction is possible for small, clean water losses under ten square feet with immediate response. Beyond that, professional moisture mapping identifies hidden saturation in wall cavities and subfloors that household fans cannot reach. For mold, the EPA recommends professional remediation for growth exceeding ten square feet. In Los Angeles’s climate, where marine layer humidity and Santa Ana dry cycles create rapid moisture migration, professional drying verification prevents the mold growth that appears months later.
You retain final responsibility for your claim, but a professional restoration contractor should coordinate directly with your adjuster - sharing documentation, attending site visits, and answering technical questions - while keeping you informed at every step. At Back to Dry, we handle adjuster communication transparently, with all documentation copied to the homeowner, but we never accept payment assignment or require direction-to-pay agreements. Your claim remains your property.
Decline, and consider it a signal to hire elsewhere. In California, AOBs transfer your right to negotiate your own claim and can result in balance billing for work you did not authorize. Back to Dry has never required an AOB in 12,000 jobs. A written scope with your signature before work begins, paid by you from insurer proceeds you receive directly, preserves your control and your recourse if disputes arise.
The Bottom Line
Hiring a restoration contractor in Los Angeles is not primarily about finding the fastest response or the lowest price. It is about controlling the documentation that determines whether your insurer pays your claim in full. Verify the CSLB license and workers’ comp in ten minutes. Insist on a written Xactimate scope before work begins. Refuse any Assignment of Benefits. Judge bids by line-item completeness, not total price. And demand daily moisture logs, dated photo records, and a final invoice that cross-references both. The contractors who resist this transparency are not saving you money - they are shifting risk to you, with interest. For more guides & resources on protecting your home and claim, explore our blog.
Written by Alicia Brennan, Owner at DryMark Restoration Los Angeles, serving Los Angeles since 2011.